


Inventories
Assuming that we still have the business cycle – something that we do assume – our grand question is, well, when’s the next turning point? A guide to the expansion faltering being when inventories start to blow out, for logically when the warehouses fill up with things unsold, then people are buying less than they were.
The underlying idea being that producers of things have highly imperfect knowledge of what people wish to buy out there, there’s a certain amount of guessing going on. The only real knowledge comes when people do buy something, but of course, that only really arrives, that knowledge, when people buy the thing. But, of course, things must be made before people buy them. So, we have inventories of things already made and waiting to be bought.
If there’s a significant change in buying, then that’s where it will first turn up – in the size of those inventories. If, say, those balloon out, then that means consumption is falling for that’s clearly a sign that what has been made to meet past demand is in excess of current demand. Or, the other way we can make the same point, demand has fallen. At which point, producers will make less and then, here we are, we’re in a recession.
Thus, keeping an eye on the monthly inventories numbers is a good idea. Currently, for all the worries about coronavirus, we see absolutely no sign of such a turning point in the economy.
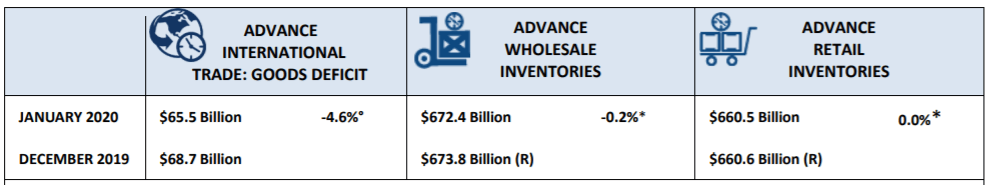
(Advance Economic Indicators from Census Bureau)
As a note, I pay very little attention to the trade numbers. Partly on Adam Smith’s grounds that worrying about the balance of trade is a silly thing to do, partly because it’s a monthly number that bounces around to no great import (sorry), and therefore, we shouldn’t place too much weight upon it as a monthly guide to how the economy is doing.
Wholesale inventories
We can have a look in a little more detail at wholesale inventories:
Wholesale inventories for January, adjusted for seasonal variations but not for price changes, were estimated at an end-of-month level of $672.4 billion, down 0.2 percent (±0.4 percent)* from December 2019, and were up 0.6 percent (±0.9 percent)* from January 2019.
This is actually a little less of an inventory buildup than we would expect to see. Note that it’s not price adjusted, so we’d expect to see the value of inventory rise in line with producer prices.
The likely explanation here is that we’ve a structural change going on – and there often are such – at the same time, as we’re looking to see cyclical changes in this number. Increased computerisation, the rise in just-in-time manufacturing, these would both lead to a fall in the stock levels across the economy. But that would be a marginal difference each month as it would be a long-term effect. More knowledge about what people are buying, influencing things with a shorter production cycle, sure, over time, we’d expect there to be less sitting in warehouses around the country.
We could thus have this structural effect lowering inventories on an annual, decadal, level while we’re still interested in any shorter-term effects, which would indicate the effects of the business cycle.
There is the idea that information is going to get so much better that we’ll actually abolish that business cycle, an idea I don’t hold with. I can imagine – would insist in fact – that the peaks and troughs will both get shallower. The Great Moderation really is a thing after all. But the entire abolition of the cycle I don’t think we’re going to get to.
Retail inventories
We’ve also the other inventories numbers, retail:
Retail inventories for January, adjusted for seasonal variations but not for price changes, were estimated at an end-of-month level of $660.5 billion, virtually unchanged (±0.2 percent)* from December 2019, and were up 0.3 percent (±0.7 percent)* from January 2019.
This is where we’d really expect to see change if the economy were on the turn. Consumers decide to keep their hands in their pockets and stop buying. Or they reduce purchases significantly, which is much the same thing. Where is that going to turn up? The stock to handle normal levels of sales has already been produced, is in the warehouses to be shipped to the stores. The sales don’t happen, the warehouses get fuller.
To complete the logical circle, if the warehouses aren’t getting fuller, then the sales haven’t stopped, and we’re not having a consumer-led economic slowdown.
My view
It is inventories which are often the harbinger of an economic slowdown. No sign of such doesn’t mean that we’re not going to have problems, only that they’re not going to come from this source.
As we can’t see any problems here, then I stick with my medium-term view. There’s nothing internal to the US economy which indicates problems with it.
Of course, there are reasons why this view may not be true. Coronavirus could be substantially worse than anyone seriously think it is at present. We have had influenza-like pandemics that were seriously damaging. Spanish flu too, perhaps 50 million people. Asian flu, in 1958, several million, and that one we can’t actually see in the economic statistics at all. So, part of it depends on how bad it all gets.
It’s also possible that something breaks in that US economy as a result of the stresses. I can’t see what it is, but then, rather the point of the study of economics is to teach you that it’s not possible to see everything in the necessary detail. There sure could be something out there I’m not paying enough attention to.
The investor view
Of course, there is always that possibility of something exogenous, something from outside the domestic economy, that might derail the expansion. At the moment, we’re all warily eyeing that coronavirus outbreak to see if that’s going to be the thing.
I take a rather contrarian view here. Sure, the disease might become pandemic. If it does, then there’s going to be a shock to the economy. But given the general health of the US economy, that shock is going to be short. We’re on the verge of the Northern Hemisphere spring which will limit any influenza-style viral spread anyway. And so, I think that, while we might have some disruption, it’s going to be short-lived, and the economy will pick up where it left off.
My opinion would be different if I could see the buildup of other problems in the American economy, but I can’t. My view is thus as it was with the UK and Brexit. The uncertainty definitely slowed growth, but the economy did reasonably well despite that. The underlying strength thus coming through when the uncertainty was lifted, that was the British experience, and I expect it to be true for the US as well.
In terms of actions, I thus think that, yes, coronavirus is a possible problem that we ought to be aware of. But, as investors, we should be looking for its passing. For then, we’ll be able to buy into what will return to being a strong market at reasonable prices.
Assuming that coronavirus is this passing blip, as I think it will be, then any market correction is just that, a correction. We’ll not see substantial drops in GDP, nor thus in profits. That just means that we can buy into good solid stocks at lower prices. Thus, the advice is to wait a little and use any drops in price as buying opportunities for those dividend paying stocks we’d like to fill the long-term portfolio with. We’ll be able to get in at lower prices, higher yields.
Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.
Recent Comments