


Materiality is a fundamental concept in corporate reporting of all kinds. A piece of information is considered material if it would influence someone’s decision. It is audience specific but ultimately it is the company that decides what information to report.
Peacock Feather Swirl Gradient Ornate Abstract fractal illustration of spiral fabulous bird isolated … [+]
In the case of financial reporting, every listed company must adhere to rigorous accounting standards for measuring and reporting on a broad range of financial information captured in the income statement, balance sheet, and footnotes. Companies listed in the U.S must also provide a “Management Discussion and Analysis.” In financial reporting, a piece of information is material if it would influence an investor’s decision. It is important to note that guidelines on materiality from the Securities and Exchange Commission (SEC) are broad and material information can be quantitative, but not financial (such as a company’s carbon emissions or percent of women in the workforce), or even qualitative (such as policies on raw material sourcing or paying a living wage). In all cases, materiality is a binary concept. A piece of information is either material (in which case it’s reported) or it isn’t (in which case it’s not).
The origins of sustainability reporting on economic, environmental, and social issues come from the work of Global Reporting Initiative (GRI) over 20 years ago. Using a stakeholder perspective, they used a different definition of materiality based on whether a company’s actions are having an important positive or negative impact on the world whether investors think this is important or not. However, investors are paying increasing attention to environmental, social, and governance (ESG) issues because they now matter to financial performance. The body of empirical evidence on this continues to grow. More recently, as investors realize the importance of the impact of their decisions at a system level, the focus of The Investment Integration Project (TIIP), the line between values-based and value-based investment decisions is beginning to blur. One implication of this is the need to develop a concept of standards for ESG materiality from both an investor perspective and a stakeholder perspective, which is the work of the Impact Management Project (IMP).
In their sustainability reporting, it is typical for companies to perform some kind of stakeholder assessment in which they gather views of a broad range of stakeholders about what they think are important. Compared to financial reporting, there are more nuances. Companies sometimes provide a “Materiality Matrix” where one axis is how important an issue is to the company from a value creation perspective and one axis is how important this issue is to aggregate stakeholder values sentiment. This suggests that there are degrees of materiality. Some companies even indicate whether the issue is growing in importance along both axes. But in the end, as with financial reporting, the company determines what information it considers important to report and whether it wants to take a binary approach or one based on a continuum of degree of materiality.
The Sustainability Accounting Standards Board (SASB), started in 2011 and for which I was the Founding Chairman, has developed a methodology based on the Sustainable Industry Classification System (SICS) to determine which of the broad range of ESG issues considered by GRI are material to investors. It encourages companies to report on them in their 10-K, sustainability report, or some other way. SASB classifies ESG issues by industry (77 organized into 11 sectors) by degree (high or medium). For example, the material issues for the iron and steel industry are GHG emissions, air quality, energy management, water and wastewater management, waste and hazardous materials management, employee health and safety, and supply chain management. The material issues for the commercial banking industry are data security, access and affordability, product design and lifecycle management, business ethics, and systemic risk management.
SASB’s Navigator tool identifies the material issues for each industry, as well as how important each one is to 13 different financial value drivers, such as revenues or operating expenses. (I will be writing more about this in a future post.) This is a very useful tool for companies as well as investors. In his most recent letter to CEOs, Larry Fink, Chairman and Chief Executive Officer of BlackRock, stated that they will be asking companies they invest in to “publish a disclosure in line with industry-specific SASB guidelines by year-end, if you have not already done so, or disclose a similar set of data in a way that is relevant to your particular business.”
Many factors determine whether an ESG issue is material for a company from the perspective of its investors. These include growing awareness of system-level effects (e.g., climate change and income inequality), changing social expectations of employees and customers (e.g., regarding recycling and gender balance in the workforce), global norms that companies voluntarily adopt (e.g., the 10 Principles of the UN Global Compact), and laws and regulations (e.g., a carbon tax and minimum wage rates). The impact of all of these factors is magnified and speeded up dramatically through the increasing transparency made possible through social media on the Internet.
null
A recent paper, “Dynamic Materiality: Measuring What Matters,” by Thomas Kuh, Andre Shepley, Greg Bala, and Michael Flowers of Truvalue Labs (an AI/big data vendor of ESG and credit risk information and to whom I’m an advisor), explores how technology is giving all stakeholders, not just shareholders, more voice in influencing what companies must consider to be material issues. In it they introduce the concepts of Dynamic Materiality and Core Materiality. These concepts have important implications for corporate reporting, ESG integration by investors, and even for how we think about industry classification systems.
Starting in January 2019 Kuh et al. started analyzing the Russell 3000 from the period 2009 through November 2019. Their data are based on constructing signals from unstructured content online. These data can be organized in a number of ways, including through the lens of the SICS™. There are three important findings from their analysis.
The first confirms the robustness of SASB’s standards which were published on November 7, 2018. As shown in Figure 1 below, for most sectors the ESG issues of interest in terms of volume of data were largely those identified as material by SASB. For nine of the 11 sectors, 70 percent or more of the volume was on issues later identified by SASB as material. In some cases, such as extractives and mineral processing, renewable resources and alternative energy, transportation, and infrastructure it was more like 90%. The notable exceptions are consumer goods (63 percent) and financials (52 percent). This is because both of these sectors have seen some big changes in what ESG issues are important to stakeholders, and ultimately to companies and investors. For example, customer privacy in consumer goods and data security in financials are much more important issues than they were 10 years ago.
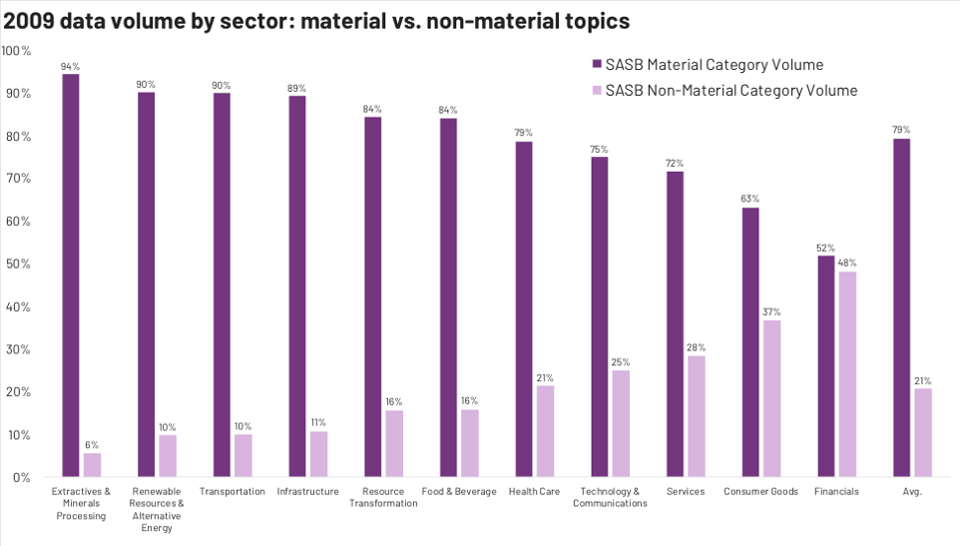
Figure 1 – The 11 Sectors in the Sustainable Industry Classification System
A similar pattern exists at the industry level as illustrated in Figure 2 for the food and beverage sector.
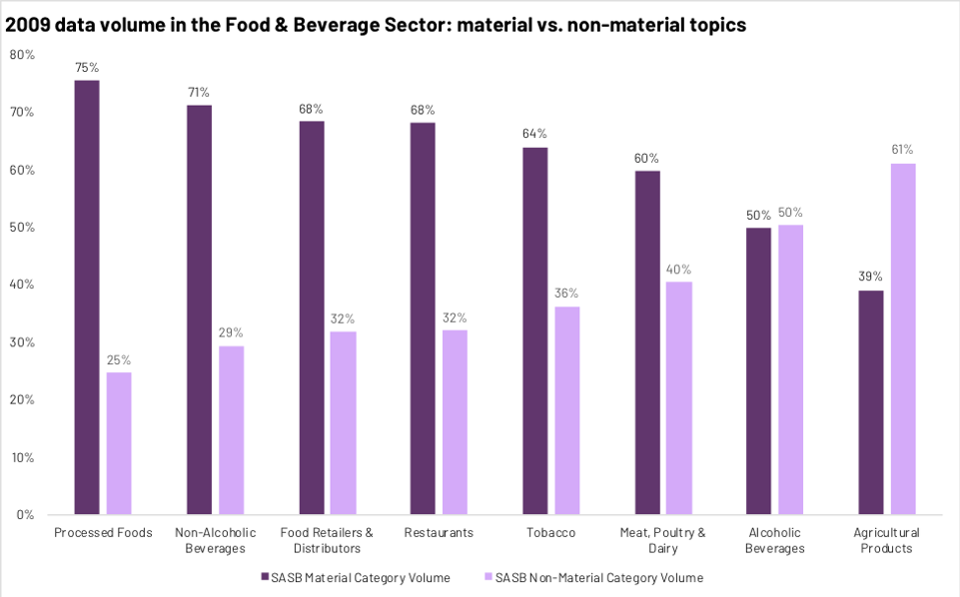
Figure 2 – The Industries in SASB’s Food and Beverage Sector
This illustrates a second important finding which is the basis of the concept of Dynamic Materiality. Due to factors such as emerging technologies, new knowledge, and new regulations companies adapt their products and services and entire industries evolve. These factors taken together with changing social expectations mean that what is material for an industry will change. There can also be differences at the company level within an industry due to different strategies. Figure 3 shows how the two issues of employee engagement, diversity, and inclusion and employee health and safety are emerging as material for the restaurants industry.
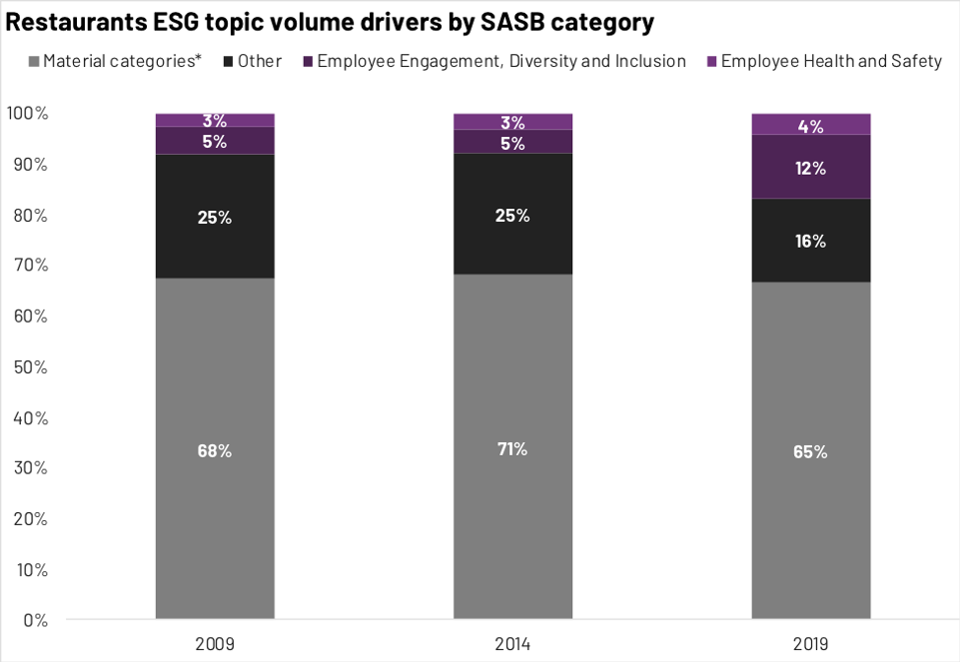
Figure 3 – ESG Issues for the Restaurants Industry
The third important finding in this paper, shown in Figure 4, is that there are three issues—GHG emissions, labor practices, and business ethics—that in aggregate have represented a fairly constant share of around 25 percent of volume for all industries taken together although they are only 11 percent of the number of SASB’s 26 categories. Kuh et al. refer to this as Core Materiality.
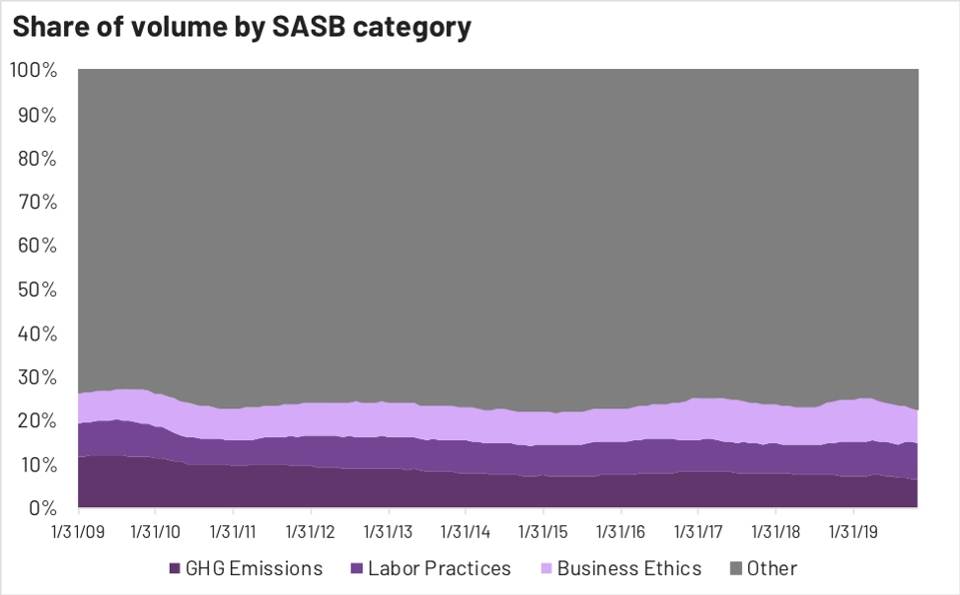
Figure 4 – The Three Core Materiality Issues
It is interesting to note that there is one each of an environmental, social, and governance issue. I would argue that each one of them is important because it deals with a system-level risk. GHG emissions are relevant to climate change, labor practices to income inequality, and business ethics to companies taking more responsibility for the negative externalities they produce through their operations, products, and services. In all three cases, society is increasingly concerned about these issues because they affect the world we live in—and ultimately whether it is a world it will be possible to live in at all. Call it values if you like, but all three issues have strong value implications. In a 3C° (or more) world, with political polarization and civil strife due to income inequality, and where companies are at risk of losing their license to operate investors will not be able to earn the returns they need for their beneficiaries.
The implications for both companies and investors are clear. The former need to develop processes for monitoring emerging material issues and reporting on them. They also need to recognize the importance of these three core issues regardless of their industry. Investors also need to be aware of emerging issues and make sure the companies in their portfolios are as well and are reporting on them. Similarly, they need to look at the system-level impacts of their portfolios and factor this into their investment decisions and engagement with portfolio companies.
Recent Comments