

Market research and consulting firm IHS Markit recently locked in its latest forecast for the North American automotive industry. Barring any major pandemic-related setbacks, most data indicate a scrappy recovery on the back end of 2020 that will continue into 2021. IHS Director of Automotive Analysis Mike Wall, who brings more than two decades’ worth of auto sector expertise, discussed the relatively surprising projections that he didn’t foresee at the start of the pandemic.
How difficult is industry forecasting and getting a clear read on the future with all of the volatility brought on by pandemic?
At this time last year when we were doing this exercise, I certainly didn’t have a global pandemic on my bingo card. When it comes to those types of events, no one is able to predict that. What we have done a decent job of, because of the data resources that we have, is trying to measure and monitor the health of the consumer and the recovery. Looking at registration data — new daily and weekly registrations — and being able to see the pace of sales certainly does help but it’s wickedly tough right now to forecast in this industry.
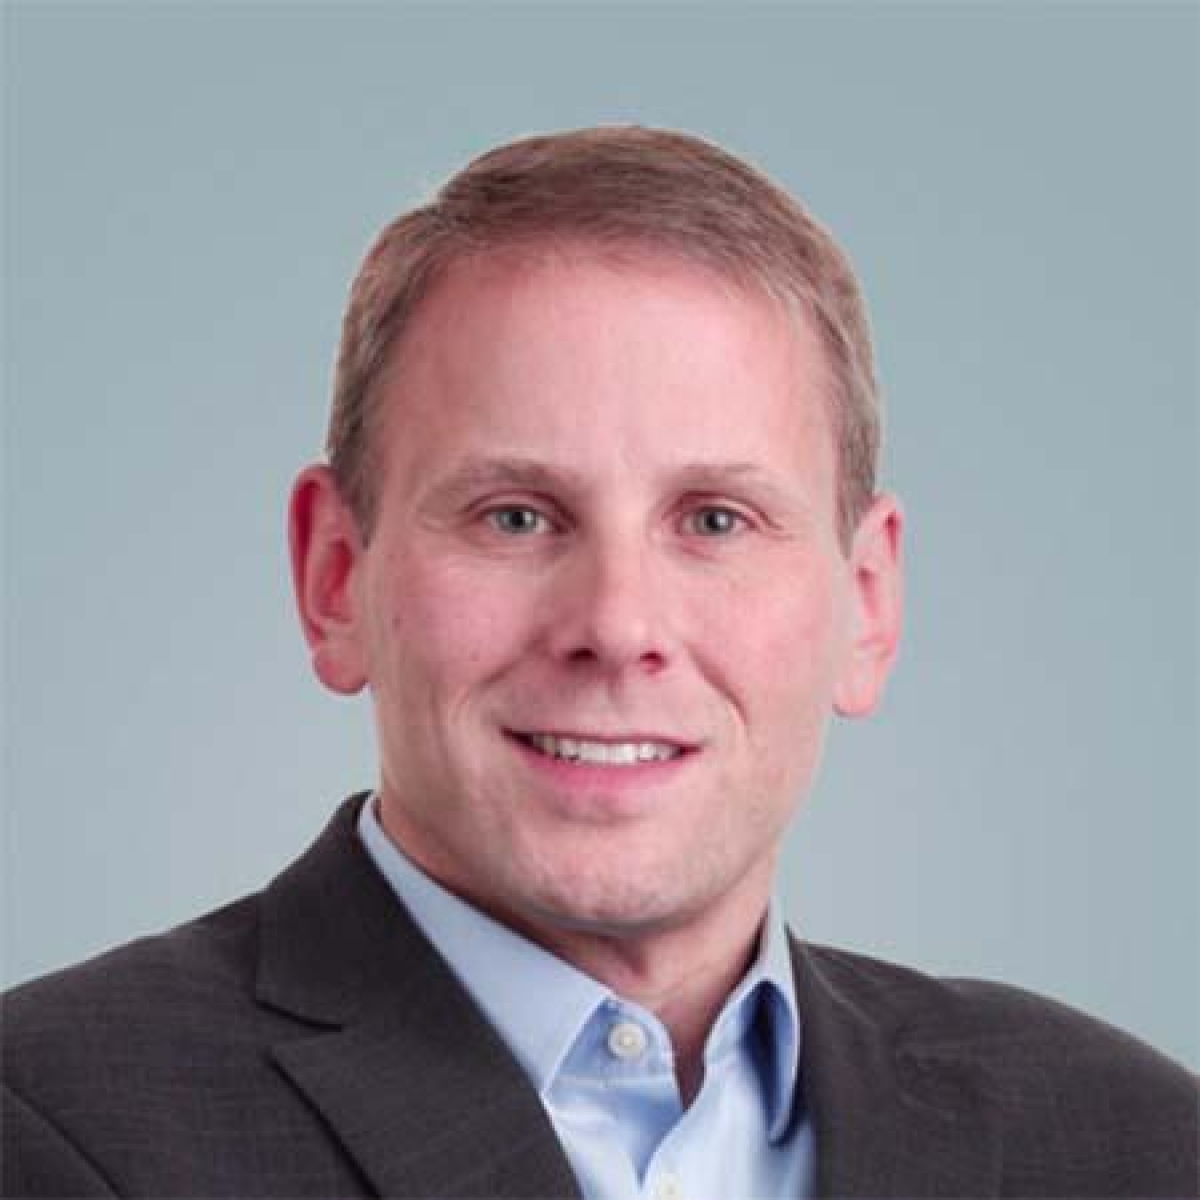
Mike Wall, director of automotive analysis at IHS Markit
COURTESY PHOTO
By all accounts, inventory is low. How does it look from where you sit?
We’re in catch up mode. We’re way under where we need to be on inventory. We’re trying to rebuild inventory in a time when retail sales have snapped back, quite frankly, to darn near pre-pandemic levels. And, by the way, we have to do all this while social distancing, restructuring our lines for COVID mitigation and all that. That’s tough. Last month was a good example. We had a decent sales month. We only grew inventory by 40,000 or 50,000 units. It was pretty modest. And yet we realistically need to rebuild inventory by maybe the tune of 500,000 or 600,000.
What are some factors holding back automakers and suppliers from rebuilding at a quicker pace?
You talk to just about any supplier and one of the biggest things they’re stressing about is labor. They can’t find people and they need more skilled labor. These COVID mitigations, there is a cost to them, but there is an impact to efficiency and we’re seeing that at the automaker level, too. It’s tough to rebuild those volumes when you have all these things operating out in the ether right now.
Other than low inventories, is anything else hampering sales numbers?
Probably the biggest headwind facing U.S. light vehicle sales is in the car rental market — those fleet sales. Certainly those are going to be depressed and quite frankly, they’re going to be depressed for a while now until air travel really comes back, which honestly will probably be a couple of years.
Per IHS reports and forecasts, the U.S. sold 17.1 million units in 2019, which was trimmed down to what will be around 14.6 million units this year. How devastating of a drop is that and where do you see us landing in 2021?
You might look at those numbers and say, ‘Wow, that’s a haircut,’ and it is. But I’ll tell you that at the depths of the pandemic we were probably closer to 12.5 million (units) for the year. The 14.6 million is reflecting — not all, but a good chunk — the fleet sales weakness that is out there. We have started to see retail sales come back to the point where our 2021 number is 16 million units. It’s not 17 (million), but a good chunk of that delta is daily rental fleet sales. If you were going to tell me in late March and April that we’d be back to 16 million units next year, I’d say good luck.
How does this recovery compare to that of the Great Recession?
When you look at the Great Recession, you look at the year 2007, which was the last sort of pre-crisis year. We had 16.2 million (units sold). We went to the depths and hit 10.4 million in 2009. We did not get back to 15 (million) until 2014. So, we’re realistically looking at next year at least getting back into the 16 million range, which is just amazing.
Recent Comments