


Kraft Heinz (NASDAQ:KHC) offers investors a huge 5.3% dividend yield at a time when the broader market’s yield is below 2%. It operates in the largely stable food industry, offering name-brand products that consumers buy every single day. And it counts Warren Buffett as a big investor. That all sounds great, but Kraft Heinz is still a terrible investment. Here’s why.
Cutting costs can’t save the day
The creation of Kraft Heinz dates back to 2015 when the two companies — Kraft Foods and H.J. Heinz — agreed to a merger. Neither one was firing on all cylinders, however. The goal was for 3G Capital, a private equity shop that basically ran Heinz, to focus on cutting costs. That was the game plan being successfully executed at Heinz at the time and it was notably improving profitability. However, management was getting to the point where it couldn’t cut much more; it needed to add another high-cost business so it could continue cutting. Thus the Kraft deal. Warren Buffett even provided a big endorsement, explaining in the press release for the agreement that he was “delighted” to play a part in the merger.
Image source: Getty Images.
Cost cutting is important; no company should operate with bloated expenses. And putting two companies with similar businesses together makes sense on this front, since it can eliminate redundant expenses. The problem is that you can’t save yourself all the way to a profit. Eventually you risk damaging the business if you aren’t also investing in the future. 3G Capital was so focused on cutting the fat that it lost sight of the big picture and its increasingly stale products started to lose consumers. It was so bad, in fact, that the company had trouble selling brands it no longer wanted after it brought in a new CEO.
A better fix
The solution to the company’s problem is pretty straightforward. It needs to cool the cost cutting and focus more on innovation. It has a stable of iconic brands to work with, so there’s a very real opportunity to turn things around. This is, in the end, what the company is trying to do.
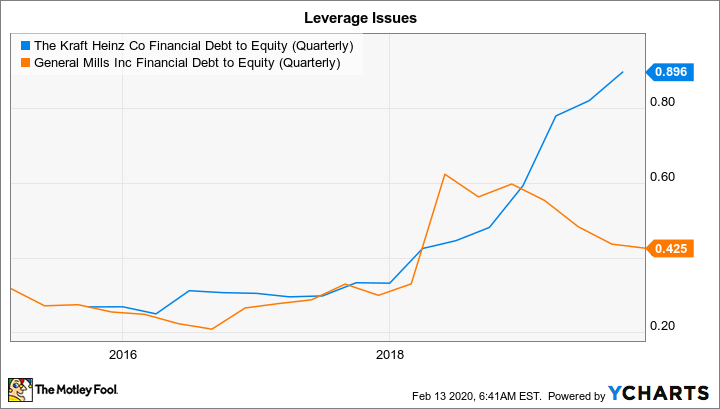
The problem is that investing for the future costs money, and Kraft Heinz isn’t in a great position on that front. It was forced to cut the dividend 36% at the start of 2019 to preserve cash. Although probably the right call for the company, dividend investors who had been relying on the company’s dividend to help cover daily expenses took a material hit. And the savings will only go so far, because Kraft Heinz has a lot of debt. At this point, the company’s financial debt-to-equity ratio is roughly 0.9 times — which is extremely high.
KHC Financial Debt to Equity (Quarterly) data by YCharts
General Mills (NYSE:GIS), for comparison, made a big acquisition of its own that led to investor worries about leverage. Its financial debt-to-equity ratio is around 0.43 times and peaked at a little over 0.6 times. The notable difference here is that General Mills bought a growing pet food business that it hoped to keep expanding, not a company with aging brands and a goal of cutting costs.
To be fair, one of the reasons Kraft Heinz’s financial debt-to-equity ratio is so bad is that it wrote down the value of its brands by about $15 billion in early 2019. Non-cash charges like this come out of retained earnings (a part of shareholders equity), which makes leverage look worse. The bigger issue here, however, is that this move was an admission that the company’s assets aren’t worth as much as management thought. And the situation hasn’t improved, with the company reporting weak earnings in 2019 and yet another impairment charge. Although the most recent quarterly charge at around $500 million is much smaller, it suggests that management still hasn’t gotten a handle on the business. As noted above, you can only cut so much before you hit bone — and it looks like Kraft Heinz may have done permanent damage to its brands. Astute investors should be wondering if that damage has been contained.
As if this weren’t bad enough, Kraft Heinz was also forced to announce that it had to restate its financial results for three years. Although the accounting issues all happened under previous leadership, the fallout from such things is never quick. Regulators are, as you might expect, eyeing the company’s books. While the future financial impact of this issue isn’t likely to be huge, it’s a statement about how far astray the company went in its cost-cutting efforts. Conservative types would be better off avoiding this headache.
Just not worth it
Even after a big dividend cut, investors can still find a fat 5.3% dividend yield at Kraft Heinz. That’s because all of the company’s troubles have led to a roughly 70% price decline from its 2018 highs. There’s probably turnaround potential here, particularly with new leadership in place. But the history is ugly and key factors (most notably leverage and a neglected brand portfolio) make fixing the business much more difficult. Most investors would be better off looking elsewhere for a high-yield investment today, noting that some financially strong and conservative midstream energy players have high yields and still solid growth prospects.
Recent Comments