


Ship owners have refrained from newbuilding ordering activity this past week, but they’ve been rather active in the S&P market. In its latest weekly report, shipbroker Banchero Costa said that it was “fairly active in the second hand market. In the dry segment, the ‘White Hawk’ 61,000 dwt built in 2012 at Oshima was sold to Greek buyers for $15.7 mln. Again, there was a Greek buyer behind the purchase of the ‘Cygnus Ocean’ 58,000 dwt built in 2013 at NACKS which was sold for $13.2 mln. The Handysize ‘Ultra Tolhuaco’ 37,000 dwt built in 2015 at Oshima was sold for $17 mln to an unknown buyer. The sale represented a benchmark for 5 years old Handysize units, was in line with the one of ‘Vanessa Oldendorff’ 38,000 dwt built in 2015 at Nakai Setoda earlier this year. In the wet segment Euronav acquired 3 x VLCCs resale from Daewoo. The vessels were sold for $93.75 mln each and they will be the first scrubber-fitted VLCCs despite the 42 VLCCs presently owned by the company. Moving to the chemical tankers, apparently Borealis Maritime bought for region $6 mln the ‘Rio Daytona’ 13,000 dwt built in 2010 by STX, the Korean yard is the only one building 13,000 dwt chemical tankers with a loa equal or under 120m. Not an intense week in the gas segment: the only vessel sold apparently was the ‘Brit Kosan’ 3,443 cbm built in 1999 by Hitachi which went to the Indonesian Waruna Nusa Sentana PT for $3.1 mln.
Source: Banchero Costa
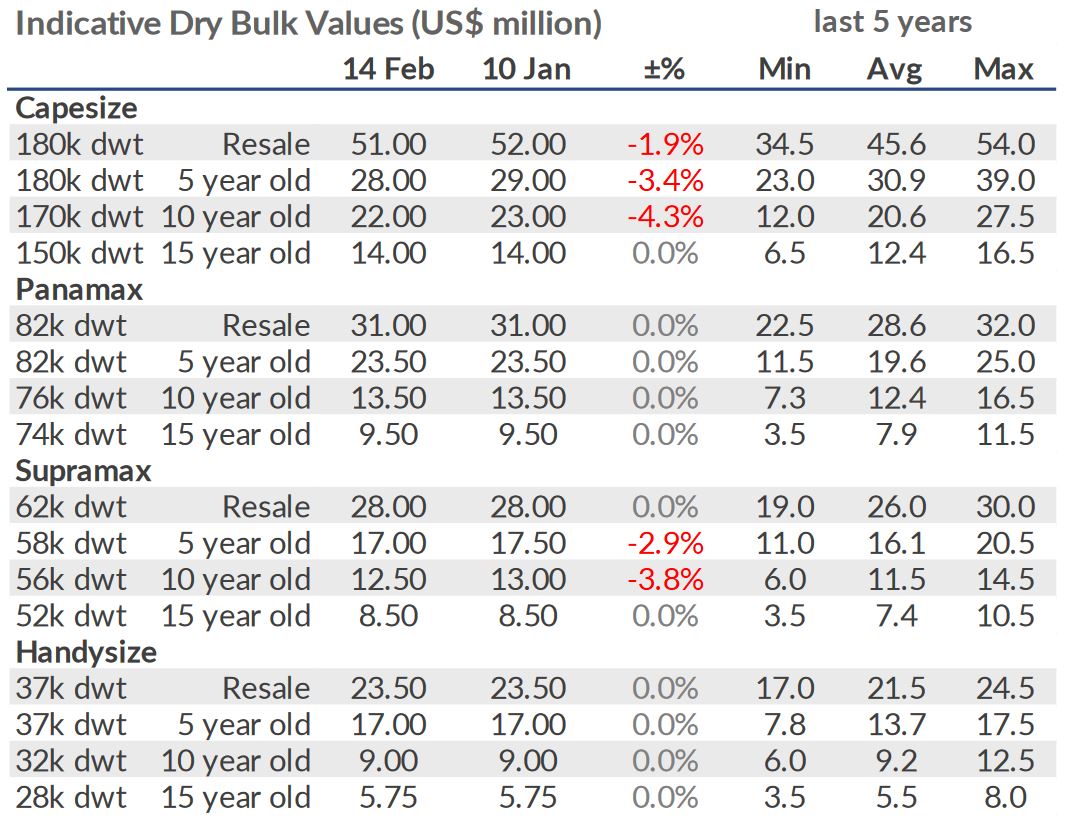
Allied Shipbroking added that “on the dry bulk side, there was a slow-down noted in activity, with the market caught up by the poor freight markets. However, there were still transactions noted last week with focus being given to Kamsarmax and Supramax units. The slightly better outlook and earnings noted in these two segments possibly make the investment choice here more attractive. Meanwhile, with prices in a sliding mode, it is expected that we will see revived interest soon, as bargain hunters will be in search of any and all opportunities to be seen. On the tankers side, the slow-down momentum was resumed this past week, with declining freight markets affecting buyers’ appetite. Last week, the most interesting deal included the resale of 3 VLCC units, while the product tanker segment was once again dominated buyers’ interest. Prices here have not yet posted any drop and in contrast have shown some slight uptick, as market participants remain optimistic even after the correction noted in freight rate levels”.
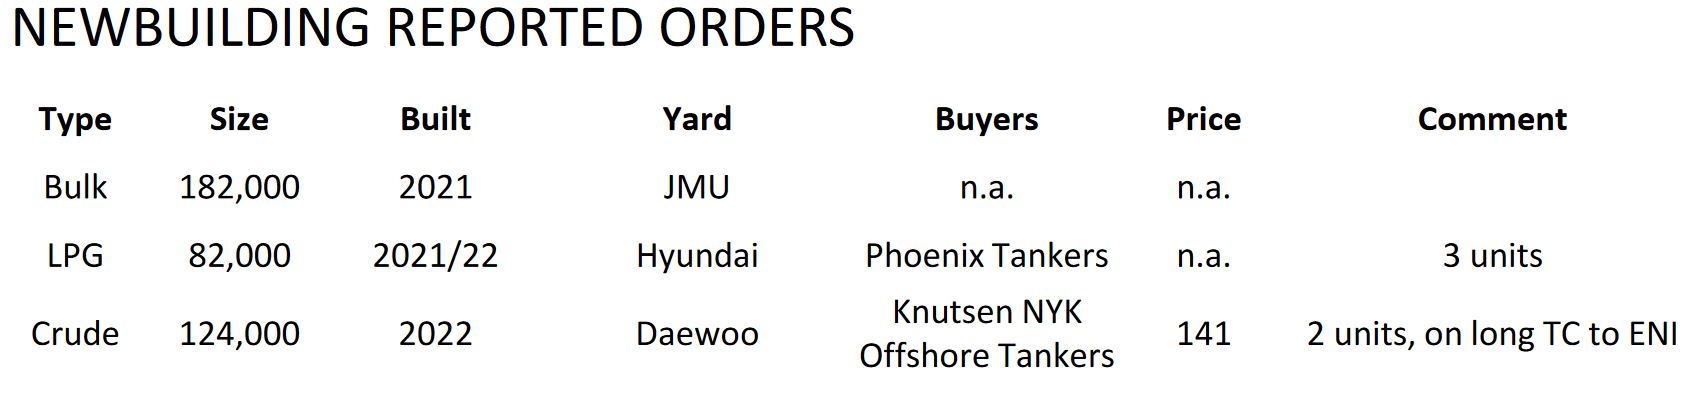
Meanwhile, in the newbuilding front, Banchero Costa said that “the activity was very quiet. Hudong received an order for 2 LNG carriers, around 80,000 cbm, from K-Line, the units are backed by a 12 years + 12 years TC to Petronas. Deliveries are set for 2Q 2022, price around $120mln each. Clients of Thenamaris declared an option for a LPG carrier of around 38,000 cbm bringing the order to a total of 4 units at Hyundai Mipo. The delivery is scheduled for 2022. A single option for MR tanker was confirmed at STX for delivery 2022 by Golden Energy. We don’t have any dry bulk NB order to report this week; activity is more focused on the scrapping of older tonnage rather than NB orders”.
Source: Banchero Costa
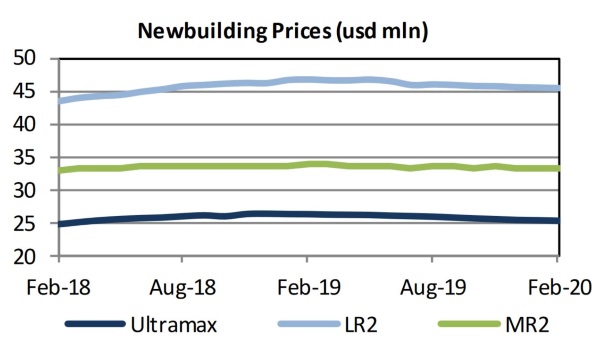
In a separate note, Allied Shipbroking added that “this was another week of limited activity in the newbuilding market, with the poor freight conditions still dominating the market sentiment. Given the current earnings levels that stands below or close to OPEX levels for most of the dry bulk segments and the downward revised prospects of the tanker segments, we do not expect any uptick being seen in buying interest for newbuildings any time soon. Interestingly enough though, prices have not fully shown yet to be following this deterioration in sentiment, a mere fact that has contributed even more in decreasing potential buyers’ appetite.
Source: Allied
Last week, we noticed just a couple of new orders in the dry bulk market, while no tanker was ordered during the same time frame. The only sector that remained relatively active was the gas sector last week. The current subdued interest pattern is expected to remain for a while, as there is little if any sign in the horizon pointing to an imminent and sharp improvement in freight markets”.
Nikos Roussanoglou, Hellenic Shipping News Worldwide
Recent Comments